Monzo’s £10 Billion Valuation Test Is Reshaping the Future of Digital Banking
After takeover talks with Nubank collapsed, Britain’s Monzo is turning to private equity investors. The shift highlights the growing tension between the ambitions of digital banks and the valuations investors are willing to pay.
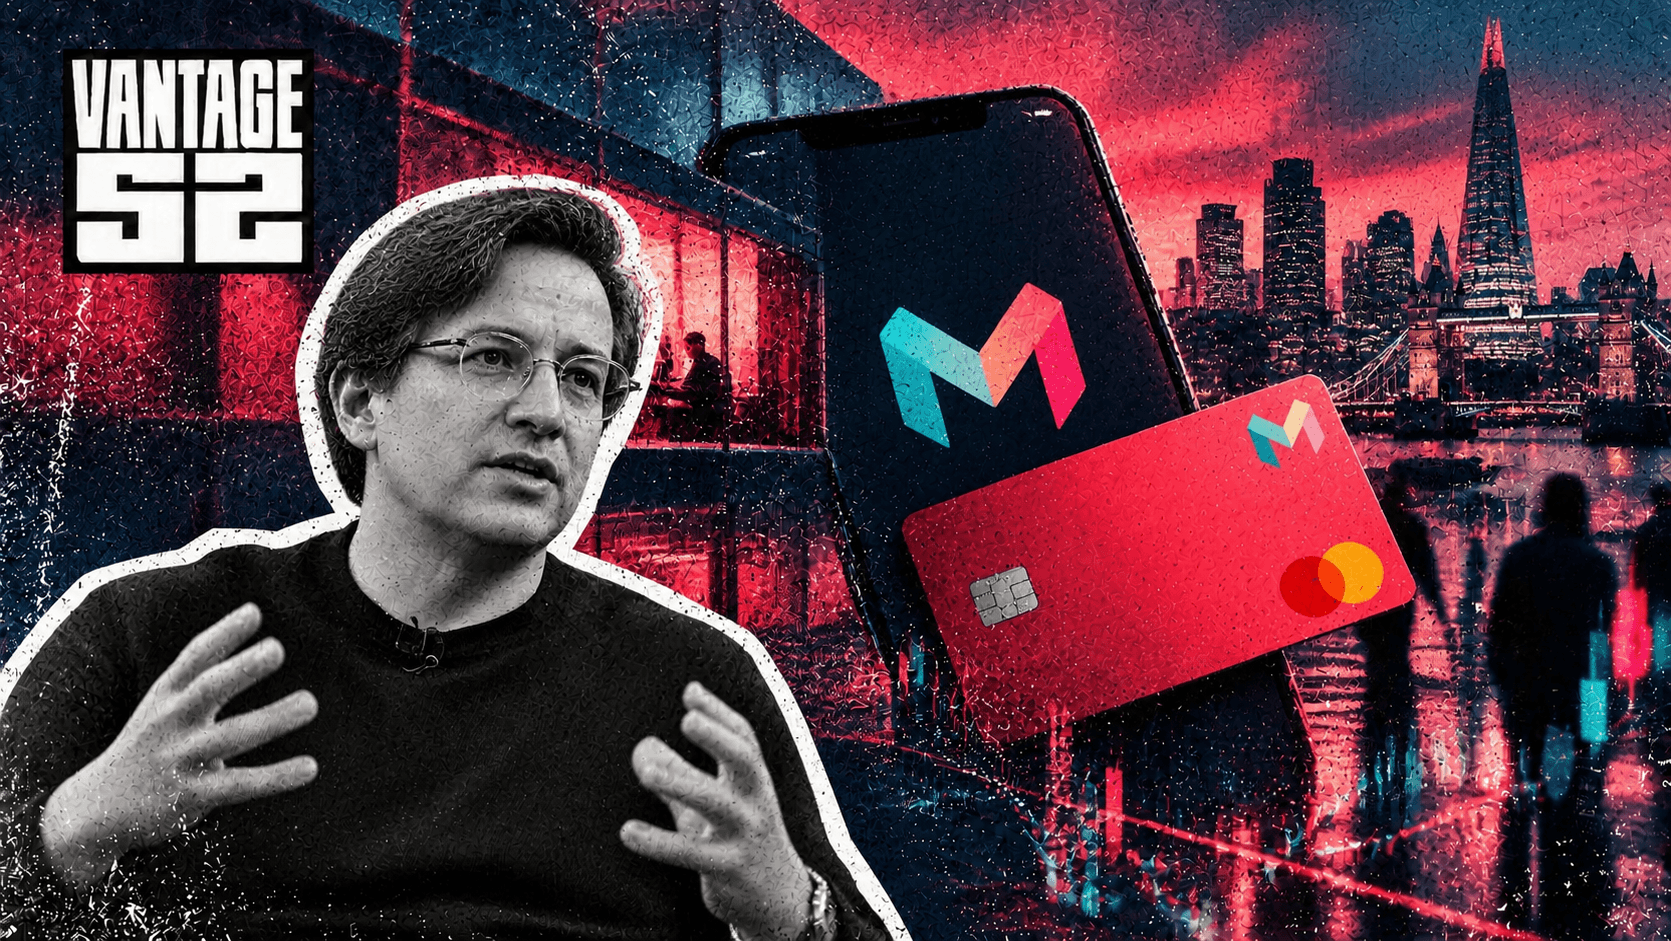
Monzo is exploring a new investment deal after acquisition talks with Brazilian digital banking group Nubank ended without an agreement, according to the Financial Times. The British fintech had been seeking a valuation of up to £10 billion, but the two companies did not reach an agreement on the proposed transaction.
Monzo is now in early-stage discussions with private equity firms CVC and Advent International about selling a stake of up to 15%. The talks remain preliminary, and no transaction has been announced.
The change in strategy reflects a different route to financing the bank’s next phase of growth. Rather than selling the business to a larger financial institution, Monzo could bring in an investor that provides capital while allowing the company to remain independent.
For Monzo, the challenge is not simply finding a buyer. It is finding an investor willing to accept its valuation and growth plans.
Why Monzo’s Valuation Became a Sticking Point
A valuation of £10 billion would place Monzo among the most valuable privately held financial technology companies in Europe. But a headline valuation does not automatically reflect the price an investor is prepared to pay.
The Financial Times reported that the proposed valuation raised questions among analysts about the relationship between Monzo’s financial performance and the price attached to the business. One concern is whether the bank can generate enough revenue from its customers to justify such a premium in the mature UK banking market.
Monzo has built a large customer base through a mobile-first model that combines current accounts, payments, savings and other financial services. Its brand and digital distribution have helped it compete with established banks without relying on the same traditional branch network.
However, customer growth and brand recognition are only part of the investment case. Investors also need to understand how effectively the company can turn those customers into sustainable revenue and profits, particularly as competition intensifies.
Private Equity Offers a Different Route to Growth
A minority investment from a private equity firm would give Monzo access to additional capital without requiring a full sale. Depending on the final structure, it could also provide strategic support as the bank expands its presence in Europe.
CVC and Advent International are established investment firms with experience in large corporate transactions. Their interest, as reported by the Financial Times, comes after Nubank stepped away from the acquisition discussions.
Yet a minority investment is not necessarily an easier transaction to complete. Private equity investors typically examine valuation, profitability, growth potential and the eventual route to an exit. Without the strategic rationale that a full acquisition might provide, a financial investor may be particularly sensitive to the price paid.
Monzo’s existing shareholders could therefore face a difficult negotiation. Raising capital at a lower valuation could dilute their ownership, while holding out for a higher price could delay the investment needed to support future expansion.
Nubank’s Decision Reflects a Different Growth Strategy
Nubank has built a major digital banking business in Latin America, serving approximately 140 million customers, according to the Financial Times. The company had considered Monzo as a possible entry point into the European market, but the acquisition would have required it to navigate a different competitive and regulatory environment.
The UK banking market is already served by established institutions and several digital challengers. Expanding into Europe would require Nubank to invest in customer acquisition, regulatory compliance, local operations and products suited to different markets.
The reported valuation was another consideration. Analysts cited by the Financial Times questioned whether Monzo’s revenue profile justified the price under discussion.
Nubank’s decision not to proceed does not necessarily signal a retreat from international growth. It illustrates that strategic expansion also depends on the terms of a transaction and whether the expected returns justify the investment.
Europe’s Digital Banking Market Faces a New Test
The Monzo negotiations come at a time when digital banks are moving beyond customer acquisition and increasingly need to demonstrate durable business models. Building a successful financial app is not the same as building a profitable bank, particularly when companies must balance attractive customer offers with the costs of funding, compliance, technology and expansion.
For investors, the distinction between growth and profitability is becoming central to valuation. A large customer base can create opportunities to sell additional financial products, but those opportunities must translate into measurable financial returns.
Monzo’s reported discussions with private equity firms will therefore be watched as a test of how investors value European fintech businesses. The outcome could help clarify whether private capital is prepared to support the next stage of digital banking expansion at the valuations sought by founders and existing shareholders.
The immediate question is whether Monzo and a potential investor can agree on the price. The broader issue is how digital banks can turn scale into sustainable financial performance without sacrificing the growth that made them attractive in the first place.
Tags
Key Concepts
Sources
Where the reporting above comes from. Follow these to check the figures and statements for yourself.